What is GST Multi-State Registration?
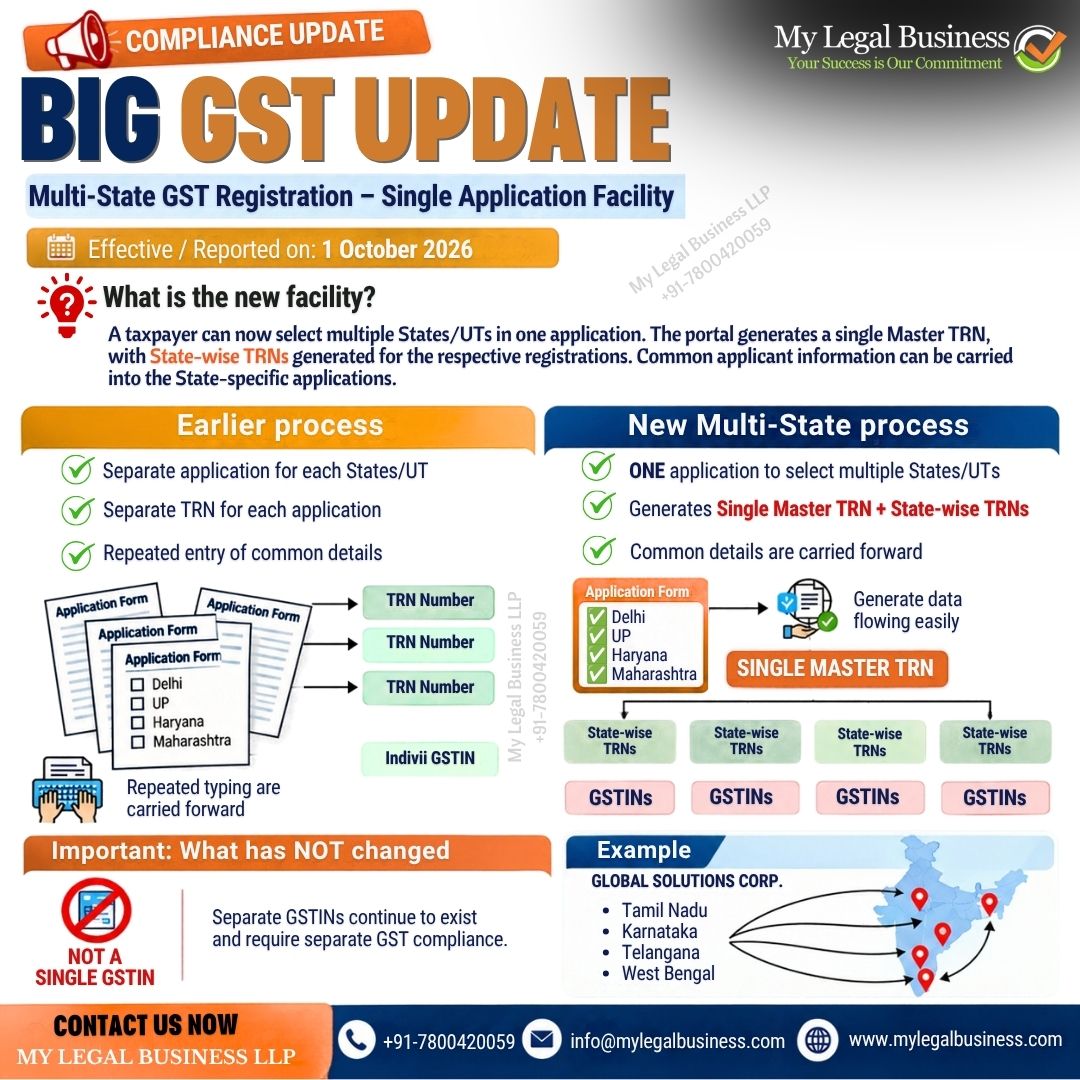
The GST Multi-State Registration facility is a new functionality introduced by GSTN that allows taxpayers requiring GST registration in more than one State or Union Territory to initiate those registrations through a single common application workflow.
The facility is currently available for Normal Taxpayers having the same PAN for registrations in multiple States/UTs.
The main objective is to eliminate repetitive data entry.
For example, if a company requires GST registration in:
- Delhi
- Uttar Pradesh
- Haryana
- Maharashtra
The taxpayer can select these States through the Multi-State Registration facility and provide common business information once.
What Has Changed from 1 October 2026?
From 1 October 2026, GSTN introduced a dedicated “Multistate Registration” option on the GST Common Portal.
Under the new process:
Multiple States/UTs → One Master TRN → Common Information Once → State-wise TRNs → Separate GST Registrations
The common information entered through the Master TRN is automatically populated into the respective State applications, reducing repetitive data entry.
How Does the New Multi-State GST Registration Work?
The process can broadly be understood in the following steps:
Step 1 – Select the States/UTs
The taxpayer accesses the Multistate Registration option on the GST Portal and selects the States/UTs where GST registration is required.
Step 2 – Enter Initial Details
Basic details such as the legal name of the business, PAN and contact details are provided for the registration process.
Step 3 – Master TRN is Generated
After the required initial verification, the GST Portal generates a Master Temporary Reference Number (Master TRN).
Step 4 – Enter Common Registration Information
The applicant uses the Master TRN to provide Common Registration Information (CRI), including business and promoter/partner-related information, authorised signatory details, authorised representative details and goods/services information.
The Master TRN is required to be submitted within 15 days.
Step 5 – State-wise TRNs are Generated
After submission of the Common Registration Information, the portal generates individual TRNs for each selected State/UT.
The common information is auto-populated into the respective State applications and remains editable.
Step 6 – Complete State-specific Details
The applicant then needs to complete the information specific to each State, including:
- Principal Place of Business
- Additional Place of Business
- State-specific information
- Aadhaar authentication
- Other applicable registration requirements
These requirements continue to be handled State-wise.
What is a Master TRN?
A Master TRN (Temporary Reference Number) is the common reference generated by the GST Portal after the taxpayer selects multiple States/UTs under the new facility.
It acts as the starting point for providing the Common Registration Information applicable to the selected State registrations.
Once the common information is submitted, separate State-specific TRNs are generated.
Simple Example
Suppose ABC Private Limited wants GST registrations in:
| State | Registration |
| Delhi | GST Registration |
| Haryana | GST Registration |
| Maharashtra | GST Registration |
| Karnataka | GST Registration |
Instead of separately entering the same common details four times, the taxpayer can initiate the process together.
Master TRN → Delhi TRN + Haryana TRN + Maharashtra TRN + Karnataka TRN
What Information is Entered Through the Master TRN?
The GSTN advisory identifies the following broad categories as part of the Common Registration Information:
- Business Details
- Promoter/Partner Details
- Authorised Signatory
- Authorised Representative
- Goods and Services
This common information is subsequently auto-populated into the respective State applications.
This can significantly reduce repetitive data entry, particularly for businesses applying for registrations in several States at the same time.
What Information Has to Be Provided State-wise?
The new facility does not eliminate State-specific requirements.
After the individual State TRNs are generated, the taxpayer must complete information relevant to each State, including:
- Principal Place of Business (PPoB)
- Additional Place of Business (APoB)
- State-specific information
- Aadhaar authentication
- Applicable supporting documents
Therefore, businesses should keep the documents relating to each State’s place of business ready before starting the process.
Does One Application Mean One GSTIN?
No.
This is one of the most important points to understand.
The new facility provides one common application workflow, but it does not create one GSTIN covering multiple States.
GST registrations continue to remain State/UT-specific.
Therefore, if a business obtains registrations in Delhi, Haryana and Maharashtra, it will continue to have separate GSTINs for those States after approval.
The new facility only simplifies the application and data-entry process.
Earlier Process vs New Multi-State Process
| Particulars | Earlier Process | New Multi-State Facility |
| States selected | One State at a time | Multiple States/UTs together |
| Common details | Re-entered for each State | Entered through common information |
| TRN | Separate TRN for each application | Master TRN followed by State-wise TRNs |
| Business details | Repetitive entry | Common information auto-populated |
| State-specific details | State-wise | State-wise |
| GSTIN | Separate for each State | Separate for each State |
| Basic objective | Individual registration | Reduced repetitive data entry |
The change is therefore mainly in the registration workflow, rather than creating a single all-India GST registration.
Who Can Use the Facility?
As per the GSTN advisory dated 1 October 2026, the facility is currently available to Normal Taxpayers seeking GST registration in multiple States/UTs under the same PAN.
Businesses that commonly operate across multiple States may find this facility particularly relevant, such as:
- E-commerce businesses
- Retail chains
- Businesses with multiple branches
- Warehousing businesses
- Logistics businesses
- Works contractors
- Companies expanding into multiple States
- Businesses maintaining establishments in different States
The applicability should always be checked against the latest functionality available on the GST Portal.
Key Benefits for Businesses
1. Reduced repetitive data entry
Common business information does not have to be entered separately from scratch for every State.
2. Simplified registration workflow
Multiple State applications can be initiated through one common process.
3. Better efficiency for professionals
Tax professionals and consultants handling registrations for businesses across multiple States can manage the common information through the Master TRN.
4. Lower possibility of repetitive typing errors
Since common information is carried forward into State-wise applications, repetitive manual entry is reduced.
5. Easier expansion
Businesses planning simultaneous expansion into multiple States can initiate their GST registration requirements through a more streamlined process.
GSTN has specifically stated that the functionality is intended to reduce repetitive data entry and facilitate ease of doing business.
Important Points to Keep in Mind
Separate GSTINs will continue
The new facility does not merge State registrations into one GSTIN.
Master TRN has a 15-day submission requirement
GSTN’s advisory states that the Master TRN is required to be submitted within 15 days.
State-wise information is still required
Details relating to the Principal Place of Business, Additional Place of Business, State-specific information and Aadhaar authentication continue to be completed for the respective applications.
Verify common information carefully
Since common information is carried into multiple State applications, applicants should carefully verify details before submission.
The facility is currently for Normal Taxpayers
The GSTN advisory currently specifies availability for Normal Taxpayers.
Frequently Asked Questions (FAQs)
Q1. What is GST Multi-State Registration?
GST Multi-State Registration is a new GST Portal functionality introduced from 1 October 2026 that allows eligible taxpayers to initiate GST registration applications for multiple States/UTs through a common workflow.
Q2. What is a Master TRN in GST?
A Master TRN is the common Temporary Reference Number generated after selecting multiple States/UTs under the Multi-State Registration facility. It is used to provide the Common Registration Information.
Q3. Is one GSTIN issued for all States?
No. Separate GSTINs continue to be issued for each State/UT after approval of the respective applications.
Q4. Can a company apply for GST registration in multiple States under the same PAN?
Yes. The new facility specifically enables taxpayers requiring registration in more than one State/UT under the same PAN to initiate the applications together.
Q5. Is the Multi-State Registration facility available to all taxpayers?
As per the 1 October 2026 GSTN advisory, the functionality is currently available to Normal Taxpayers.
Q6. What information is entered through the Master TRN?
Common Registration Information includes business details, promoter/partner details, authorised signatory, authorised representative and goods and services information.
Q7. What details need to be completed separately for each State?
The applicant must provide State-specific details such as the Principal Place of Business, Additional Place of Business, State-specific information and Aadhaar authentication.
Q8. Is the Master TRN valid indefinitely?
No. GSTN’s advisory states that the Master TRN is required to be submitted within 15 days.
Conclusion
The introduction of the GST Multi-State Registration facility from 1 October 2026 is an important GST Portal process improvement for businesses requiring registrations across multiple States and Union Territories.
Enter common information once through the Master TRN and continue with separate State-wise applications.
However, taxpayers should remember that GST registration remains State-wise and separate GSTINs will continue to exist for each State/UT.
Businesses planning expansion across multiple States should therefore understand the new workflow and ensure that their common as well as State-specific information and supporting documents are accurate before submitting their applications.
ALSO READ
GST Registration for Private Limited Company
Top 10 Common Mistakes Businesses Make During GST Filing
Step-by-step Process of GST Registration